

Why Your Money Works Harder in a SACCO Than a Traditional Bank

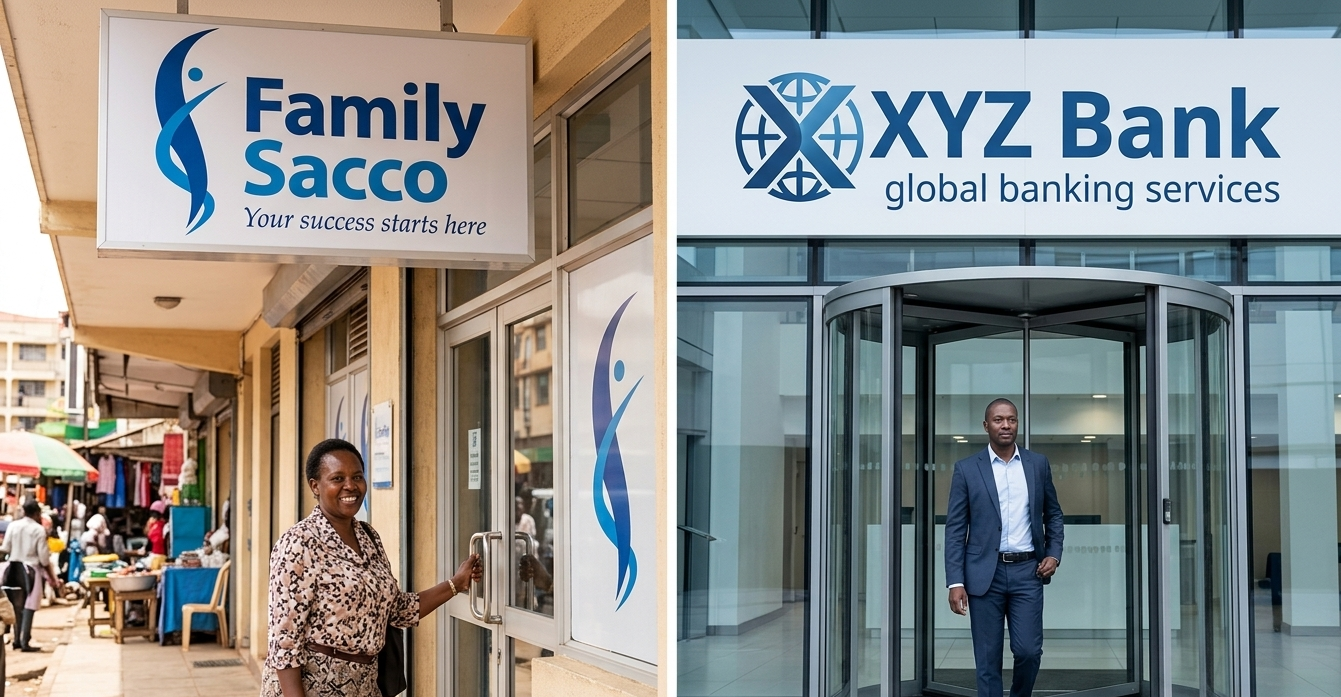
We’ve all been there: you open your banking app at the end of the month, only to notice a string of small, frustrating deductions. Account maintenance fees, ledger fees, SMS alert charges… the list goes on. Meanwhile, the interest your savings earned looks more like a mistake than a reward.
If you are looking for a smarter way to build wealth, secure your family’s future, or fund a business, it is time to look beyond traditional commercial banks.
Savings and Credit Cooperative Organizations (SACCOs)—like Family Sacco—are quietly changing the game. But what exactly makes a SACCO a better home for your money than a commercial bank? Let’s break down the main differences.
1. You Are an Owner, Not Just a Customer
When you open an account with a commercial bank, you are simply a customer. The bank’s main goal is to generate profits for its external corporate shareholders.
A SACCO operates on an entirely different philosophy: together we grow. When you join Family Sacco, you purchase shares. This officially makes you a co-owner of the institution. Decisions are made democratically, and the primary objective is to serve your financial well-being, not an anonymous board of investors.
2. The Power of Dividends and Rebates
Because banks prioritize their shareholders, the profits they make leave the community. In a SACCO, those profits come right back to you.
At the end of every financial year, SACCOs distribute surplus profits to their members in two ways:
- Dividends: Paid out based on the shares you own.
- Rebates: Paid out as a percentage of your total deposits or savings.
While a traditional bank savings account might offer a meager 2% to 4% annual interest, top-performing SACCOs regularly provide returns ranging between 8% and 15% on your money. Family Sacco provides returns of 10%.
3. Access to Cheaper, Flexible Credit
This is where SACCOs truly outshine banks. When you need a loan from a bank, you face rigid credit scoring, mountains of paperwork, and high, volatile interest rates.
SACCOs use a multiplier system (usually 3x or 4x your total savings) to determine your loan limit. Family Sacco uses a 3x multiplier system.
| Feature | Traditional Bank | Family Sacco |
| Loan Limit | Dependent on strict salary/collateral valuation | Usually 3 to 4 times your total savings |
| Interest Rates | Higher, fluctuates with market dynamics | Lower, typically stable and transparent |
| Collateral | Hard assets required (Title deeds, logbooks) | Flexible options, including peer guarantors |
| Profit Sharing | Kept by external investors | Distributed back to you via annual dividends |
4. A Community That Supports Your Goals
Banks are transactional; SACCOs are relational. Because SACCO members often share a common bond—whether through community, family, or profession—there is a deep layer of mutual trust.
If you are short on traditional collateral like land or a car logbook to secure a loan, SACCOs allow for peer guarantors. Your fellow members can co-sign and back your loan based on your character and track record within the community. Try asking a commercial bank manager to approve a loan based on your good character!
The Golden Rule of SACCO Wealth: Consistency is everything. You don’t need a massive lump sum to start making an impact. Regular, monthly contributions build your borrowing power and maximize your end-of-year dividend payouts.
Ready to Make the Switch?
Traditional banks have their place for day-to-day transactions, but when it comes to true wealth accumulation and affordable credit, the cooperative model is hard to beat. By saving with Family Sacco, you aren’t just storing your money—you’re investing in your own community and securing a higher return on every single shilling.
Ready to start your journey toward true financial freedom? Contact us or visit our offices to become a member today!
